All Categories
Featured

How Term Life Insurance Works
Nationwide also provides you the capability to basically purchase additional upside potential with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage financial investment techniques, which feature an extra 1%-2% fee. Although this reduces an IUL's floor listed below 0%, there may be years when you desire the additional benefit capacity. Varied Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Caring For Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-term development, however lackluster early money valuesParticipating policy loan rate is topped to be no higher than 8% Columbus Life Insurance Coverage is the IUL arm of the well-rated insurance coverage conglomerate of Western Southern Group, which entered the IUL arms race in the middle of the last decade.
Given that their only obligation as a business is to the long-lasting responsibility of policyholders, they are most likely to do right by their inforce block of organization. This can be plainly seen in this screenshot we recently sent to among our customers revealing how Columbus Life's IUL cap rates have actually gradually increased from 8.75% in December 2022 to 10% precisely one year later as rates ticked up.
The worst IUL companies constantly declare to have the very best Indexed Universal Life insurance coverage policy with the highest cap. They'll start with an extremely high cap to capture market share, then quickly pull the carpet out from under their consumers once they shelve that item and begin a new one.
That method, policyholders borrowing for outside financial investment opportunities still had the potential to make a minimum of some positive arbitrage. Strong S&P 500 cap rateParticipating loan rate is capped at 6% (but has been lower for a while)Their recorded history of treating in-force insurance policy holders fairlyMutual Holding Company without any outdoors stockholdersTheir uncapped indexed account is currently unsightly and inactionable.
To clarify, all the finest IUL companies in this short article offer some sort of free chronic health problem rider, however National Life Group's is probably the most robust. I also desire to point out that I am particularly discussing their "Peak Life" product, which is their "larger case" item using a more structured cost structure.
Term vs Whole Life Insurance Comparison
Technically the rider is "free", however we've discovered when stress-testing charges that the death expenses are a bit higher than other of the best IUL business."That stated, National Life Group is in the running for the best Indexed Universal Life insurance company for clients looking for a balance of performance, earnings, and extensive defense.
Don't spend too much time on these details as your numbers will definitely differ, but this shows the type of persistent illness rider payments they provide. to learn which are currently the very best IUL policies with robust Persistent Health problem Riders and solid IUL crediting methods for tax-free earnings if you don't become too sick or injured to operate individually.
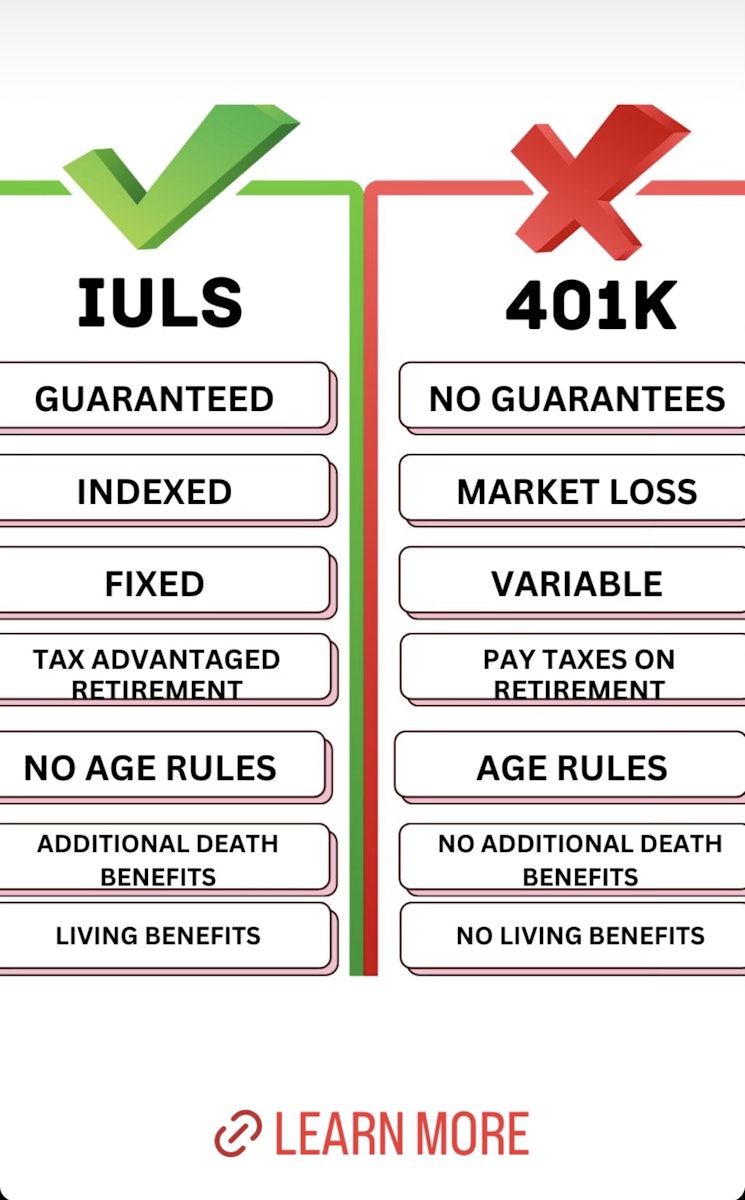
Indexed Universal Life Insurance coverage has so numerous moving parts at its core, not to point out all the possible bells and whistles different companies add to their policies. If you're weighing IUL against your existing retirement accounts, our full breakdown of covers the crucial distinctions in contribution limitations, tax treatment, and versatility.
Throughout the majority of the 1900s the only life insurance products were Whole Life and Term. Term insurance coverage supplied lower expenses for short-lived life insurance protection. Whole Life supplied a guaranteed death benefit for an ensured level premium, however also had an attached cost savings component with an ensured permanent growth rate in addition to non-guaranteed dividends.
Medicare in OrangeSelecting 2026 Medicare Options
The idea with Universal Life is that the development of the savings account will reduce the quantity of pure insurance coverage in the policy, which would reduce the rising cost per system of death benefit. In 1986, shortly after the meteoric rise of Universal Life, life insurance business had the concept of including an investment component.
This resulted in the internal revenue service restricting just how much premium anybody could pump into any quantity of irreversible death benefit for future tax-free retirement earnings. Regardless, as the stock market raged on throughout the 1990s, VUL ended up being the insurance item of option for cash build-up. In 1997, the first Indexed Universal Life product was invented by TransAmerica (not on the list of 2026 Best IUL business). In the beginning, Indexed Universal Life insurance coverage didn't make a huge splash at all.

Latest Posts

Securing Cheap 2026 Family Health Insurance
Life Insurance for Veterans Planning

Getting Fast Individual Health Insurance Quotes